In The Cattle Markets
Contributing Organizations

November 11, 2026
Andrew Anderson, Ph.D.
Assistant Professor and
Extension Specialist in Livestock Economics
Department of Agricultural and Resource Economics
Utah State University
Revisiting the Price Impacts of the Ground Beef Tariff Waiver
In the August 31 issue, I gave my estimates of the potential price impacts of the announced tariff waiver on lean beef imports, formally a temporary expansion of the tariff-rate quota that allows an additional 300,000 metric tons of beef to enter at the lower tariff from September 1 through November 30. I estimated that the policy would lower fed cattle prices by 1.5 to 3%, cull cow prices by 5 to 10%, and ground beef prices by 8 to 15%. I also noted that it would be difficult to isolate the effect of this policy from everything else moving cattle markets. In this article, I am attempting to do just that—isolate the impact so far.
Simply comparing prices before and after September 1 would not tell us much, because many other things are also driving price changes, including seasonal price patterns. Instead, I built statistical models using data from 2003 to 2026 that predict where each price would have gone from August based only on other factors: cattle on feed, beef production, feed costs, beef demand, etc. The gap between the actual price and that prediction is my estimate of the policy’s effect. Some predictions include only September because of data availability.
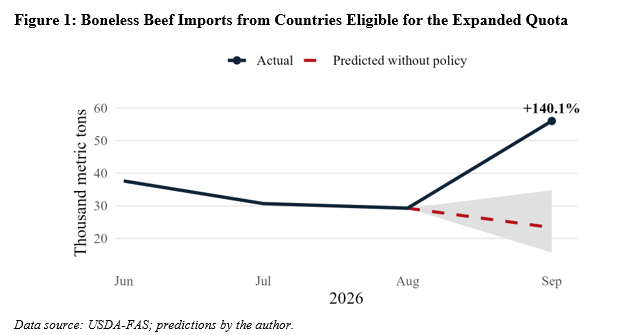
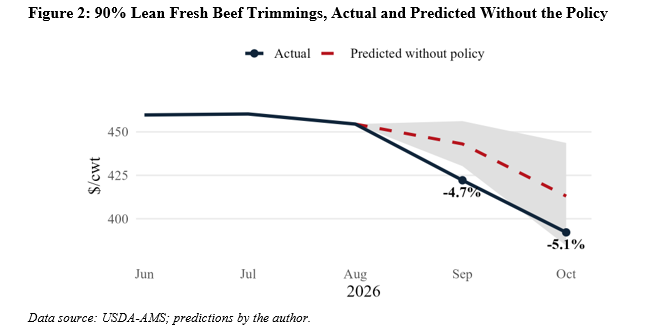
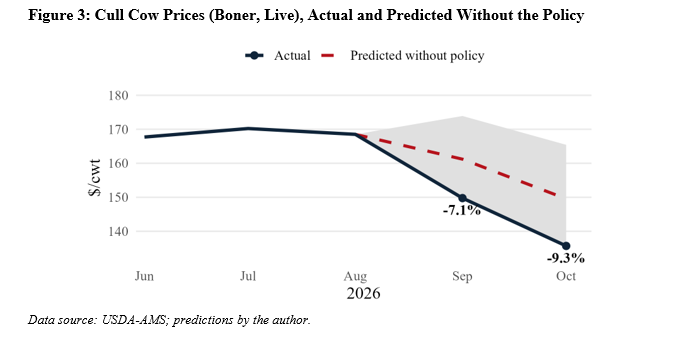
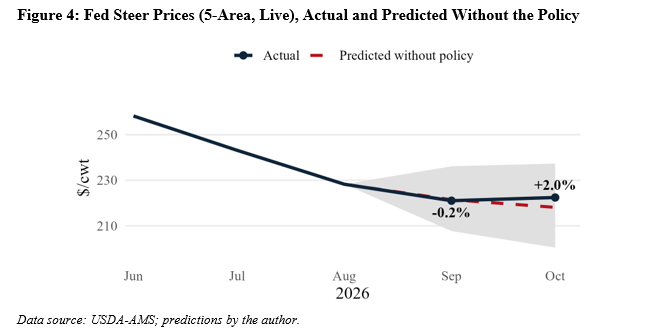
In each of the figures below, the solid line is the actual price, and the dashed line is what the model predicted without the policy. The shaded area is an 80% error range. When the actual price falls outside the shaded area, the gap is larger than ordinary market noise and likely reflects the policy. When it falls inside, a smaller effect may still be present, but we cannot say so with much confidence.
The first question is how much additional beef actually arrived. Imports of boneless beef from countries eligible for the expanded quota, mostly Brazil and Paraguay, were 56,000 metric tons in September, compared with about 23,300 tons predicted without the policy (Figure 1). That is roughly 33,000 tons of additional beef in one month. Customs data show 37,486 tons entered under the first 100,000-ton tranche, so most of the quota beef appears to be new beef rather than beef that would have arrived anyway. As I thought in August, the additional beef was below the announced volume. However, it was even lower (33%) than my “low” scenario (40%).
In terms of price impacts, domestic 90% lean trimmings were about $21/cwt, or 5%, below their predicted level in both September and October (Figure 2), and the September gap is outside the error range. So it does appear that the additional quantity of imported beef did push prices down, even beyond the seasonal decline that could be expected.
Cull cow prices followed, coming in 7.1% below predicted in September and 9.3% below in October, right on the edge of the error range (Figure 3). That falls within my 5 to 10% estimate and works out to roughly $140 to $165 per head on a 1,200-pound cow.
Fed steer prices were slightly above their predicted level in both months (Figure 4), although well within the error range, so we cannot make any strong statements here. The general decline in fed cattle prices since June started well before the policy and likely reflects factors other than the policy we are discussing here.
Retail ground beef prices have only declined slightly relative to the prediction. They were 1.4% below the predicted level in September and 1.2% below in October, or 8 to 10 cents per pound (Figure 5). Those gaps are within the model’s error range, so I cannot say with confidence whether the policy has lowered retail ground beef prices slightly or not at all. However, it does appear that lower prices were not fully (or are yet to be) passed on to consumers.
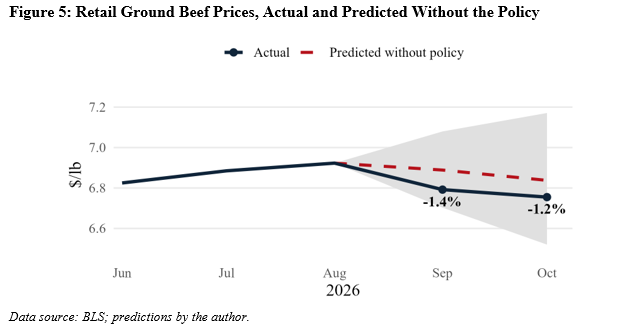
In summary, two months in, the policy has brought in a meaningful amount of additional lean beef and lowered wholesale lean beef and cull cow prices. It has not yet produced measurable savings for consumers, and any effect on fed cattle has been too small to detect. So far, the cost has fallen mainly on producers selling cull cows this fall. These effects take time to work through the supply chain, so retail prices could still follow wholesale prices lower, and the final tranche runs through November 30. So this review of the impacts is more intermediate than final.
For more details on the methods of the analysis in this article, please reach out to me at a.anderson@usu.edu.
The Markets
| Week of 11/6/26 | Week of 10/30/26 | Week of 11/7/25 | ||
| 5-Area Fed Steer | all grades, live weight, $/cwt | $215.43 | $223.73 | $228.70 |
| all grades, dressed weight, $/cwt | $338.39 | $352.19 | $358.33 | |
| Boxed Beef | Choice Value, 600-900 lb., $/cwt | $363.02 | $368.52 | $377.89 |
| Choice-Select Spread, $/cwt | $7.85 | $13.47 | $17.23 | |
| 700-800 lb. Feeder Steer | Montana 3-market, $/cwt | $350.00 | — | — |
| Nebraska 7-market, $/cwt | $349.48 | $372.75 | $354.53 | |
| Oklahoma 8-market, $/cwt | $346.50 | $361.80 | $340.90 | |
| 500-600 lb. Feeder Steer | Montana 3-market, $/cwt | $452.00 | $450.25 | $428.90 |
| Nebraska 7-market, $/cwt | $437.09 | $458.40 | $439.99 | |
| Oklahoma 8-market, $/cwt | $426.57 | $437.38 | $429.48 | |
| Feed Grains | Corn, Omaha, NE, $/bu (Thursday) | $4.19 | $4.26 | $4.05 |
| DDGS, Nebraska, $/ton | $191.25 | $202.50 | $149.14 | |
Data Source: USDA-AMS Market News as compiled by LMIC